5.0 Google · Read client reviews

Self-employed · Investors · Complex income

Complex mortgage.
Clear path forward.

Austin mortgage broker for business owners, real estate investors, and borrowers with substantial assets or complex income.

First home or a simple refinance? I help with those too.

Adam Styer

Adam Styer · Senior Loan Officer
NMLS #513013 · Company NMLS #2653540

1,000+Loans closed
5.0 ★Google · 99 reviews 4.98 ★Zillow · 45 reviews
40+Capital partners

Real files · Austin

Mortgages your bank said no to.

Being declined by one bank rarely means you can’t get a mortgage. It usually means you were sent down the wrong path. A few recent examples:

Self-employed jumbo

$1.2M Westlake purchase after 3 banks declined

The problem: An S-corp owner whose write-offs shrank his tax-return income. Banks saw low W-2 wages and said no.

The fix: A 24-month bank statement loan that counted real business deposits instead of taxable income.

Closed within 0.25% of conventional pricing.
DSCR investor

4 Austin short-term rentals, no personal income docs

The problem: An investor scaling past the conventional limit on financed properties, with tax returns that couldn’t support it.

The fix: DSCR loans qualified on each property’s rent, titled in an LLC.

Three closed in 60 days; the fourth the next month.

Move-up buyer

Their home’s sale fell apart. They still closed.

The problem: The buyers of their current home walked away mid-transaction, taking the down payment and the payment exclusion with them.

The fix: A guaranteed backup contract on the old home, plus a 75-20-5 structure so they closed with 5% down and pay off the second loan when the home sells.

Closed on the new home without waiting to sell.

Composite scenarios based on files Adam has closed; names and exact figures changed for privacy. Every file depends on full underwriting.

See My Options More real scenarios →

A mortgage that fits your financial picture.

Buying a home or refinancing with traditional income? See all mortgage options. Compare home equity financing · Buying before you sell.

Client and Partner Reviews

"Adam came highly recommended and he was exceptional to work with! He was incredibly responsive and helpful throughout the entire mortgage process."

M
Mary Cairnie
Google • 5 Stars

“I am self-employed and my loan was not straight forward.”

S
Sherita Steffe
Google • Self-employed

“I’m self-employed and when other lenders declined to underwrite a mortgage, Adam saved the day!”

E
Ellery Wren
Google • Non-QM

"I've known Adam Styer for the past four years, and he has consistently proven to be one of the most knowledgeable, reliable, and supportive mortgage professionals I've worked with."

J
Jeanne Miller
Google • Realtor Partner

"Adam is awesome - he works to understand your needs, presents multiple and often creative financing options to meet them, and supports you throughout the whole home purchase."

M
Matthew Latimer
Google • Purchase
Adam Styer, Senior Loan Officer in Austin, Texas
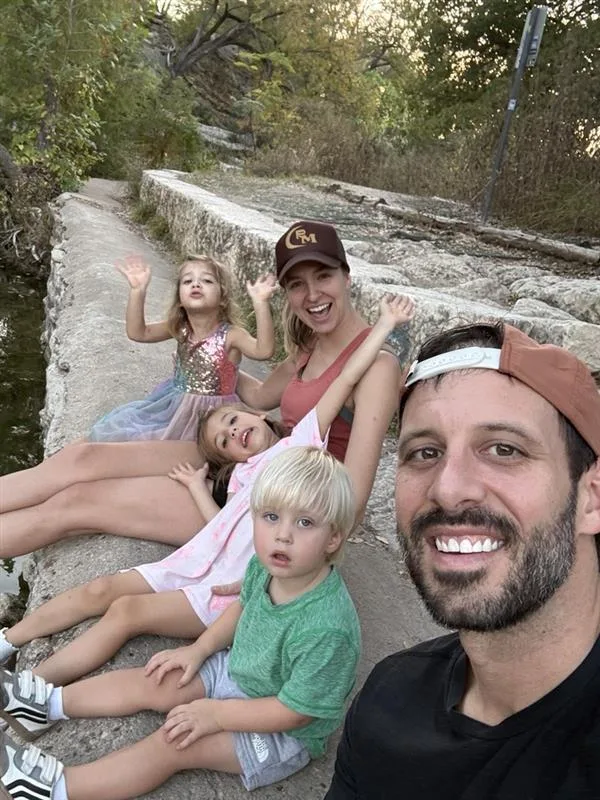
Adam with his wife and kids on a Hill Country hike

Meet Adam Styer

Adam is an Austin mortgage broker with HyperSmart Home Loans, serving borrowers across Texas. He compares income documentation, financing structure and lender options for business owners, investors and borrowers with substantial assets.

Husband, dad of three, and an Austinite for 16+ years. Faith, family, fitness and finance drive everything he does.

Meet Adam · Read real scenario reviews · Realtor partners

Based in Austin. Serving borrowers across Texas. Explore Austin-area communities →

Frequently Asked Questions

Yes. Self-employed Austin borrowers can qualify on 12 or 24 months of bank statements, a 1099-only program, a CPA-prepared P&L, or eligible assets. These non-QM programs start from the money your business brings in, not the income your write-offs reduced. Bank statement purchases reach 90% loan-to-value on the strongest files, with minimum credit of 620 to 660.

A DSCR loan qualifies a real estate investor on the property’s rental income instead of personal income. DSCR = rent ÷ the full housing payment (PITIA). Many programs prefer 1.0 or higher, but below-0.75 and no-ratio options exist. Down payments start at 20% to 25%, there’s no cap on properties owned, and LLC vesting is allowed.

Asset depletion turns eligible assets into qualifying income by dividing them by 36, 60 or 84 months, depending on the program. Cash counts at 100%, marketable securities at 80% to 90%, and retirement accounts at 70% before age 59½. It fits retirees, business owners after a sale, and anyone whose balance sheet is stronger than their W-2.

Self-employed owners, K‑1 partners, investors and high-net-worth borrowers can use bank statement, 1099-only, P&L, asset depletion, DSCR and jumbo financing (above $832,750 in Travis County for 2026). Adam compares programs across 40+ capital partners for each scenario.

Most pre-approvals are issued within one business day once the file is complete. Closing timelines for bank statement, DSCR and other non-QM loans depend on the program, appraisal, title and how quickly documents come in. See your options or call (512) 956-6010.

Let’s plan your next move.

Start with your financing goal. I’ll help you understand your options and decide what comes next.

Prefer to talk? Call or text (512) 956-6010.